Turn your mortgage into a wealth-building tool. Smith Manoeuvre strategies, tax-smart planning, and honest math from two Canadian mortgage strategists.
Co-Buying a Home With a Friend Works Until Someone Wants Out
Picture two siblings, a few years after they bought a semi together in Grimsby. One has a new job in Ottawa and needs her share of the down payment back to buy there. The other loves the house, has a garden in, and never planned to leave. Neither of them did anything wrong, and both of them are about to find out that the deal they signed covered how to buy the house and said nothing about how one of them gets out. Planning for the day your futures split protects the purchase and the relationship.
If you've been texting listings back and forth with a friend or a brother, you probably know the relief of adding your savings together and seeing a real house come into reach. You may also know the small, awkward pause when you think about asking, "What if one of us wants out?" It feels like doubting the friendship before you've even moved in. Have that conversation anyway.
What happens when only one of you wants to sell
Pooling money works. Ontario's own guide to co-owning a home makes the point that combining resources can make ownership more affordable and open up neighbourhoods neither of you could buy in alone. Go back to the siblings. The same pooled down payment that got them in is now the thing they're fighting over. One needs that money freed up. The other needs the roof over her head.
Most co-buyers assume their ownership split will settle it. Say it's 50/50, or 60/40 because one person put in more. That percentage tells you who gets what share of the proceeds. It doesn't tell you what the house is worth today, who picks the appraiser, how long the person staying has to come up with the money, or who pays the real estate commission and legal fees if it has to be listed. Promising to be fair to each other leaves every one of those questions open, and they always come up at the worst moment.
Before you buy, sit down with an Ontario real estate lawyer and get answers to these in writing:
What are our ownership shares, and how do we record unequal down payments?
Who pays what each month, and what happens if one of us falls behind?
How does an exit start, and how much notice is required?
How is the home valued, and how is a buyout calculated?
How long does the remaining owner have to arrange financing?
If no buyout happens, how is the home sold, who pays the costs, and who covers the mortgage until it closes?
Why a buyout agreement may not get you off the mortgage
Suppose the siblings get all of that right. They agree on a value and a buyout figure, and the sister staying is ready to pay. The lender still has a say.
When you borrow together, lenders typically treat you as jointly and severally liable. That means each of you can be on the hook for the entire mortgage, regardless of your ownership share. Moving out doesn't change that, and neither does a private agreement between the two of you. The sister leaving for Ottawa stays responsible for the full debt until the lender formally releases her, usually through a refinance in the other sister's name alone. That only works if the sister staying qualifies to carry the whole mortgage on her own income. If she doesn't, the lender can say no, and the person who left may still see that debt counted against her when she applies for her next mortgage.
So the agreement needs one more piece: a clear fallback for when a buyout can't get approved, usually a sale on set terms. That's the lesson under all of this. Buying together only works long term if you also agree on how to stop owning together.
Writing down an exit plan doesn't mean you expect the friendship to fail. It gives you rules you agreed on while you still liked each other, so you never have to make them up in the middle of a fight. You can still buy together, and you can do it with a plan that holds when life moves one of you somewhere else.
A good first step is a short conversation with me about whether either of you could realistically take over the mortgage alone, and what that refinance would need. Pair it with a lawyer who can put your exit terms on paper, and you'll know before you buy how this ends well.

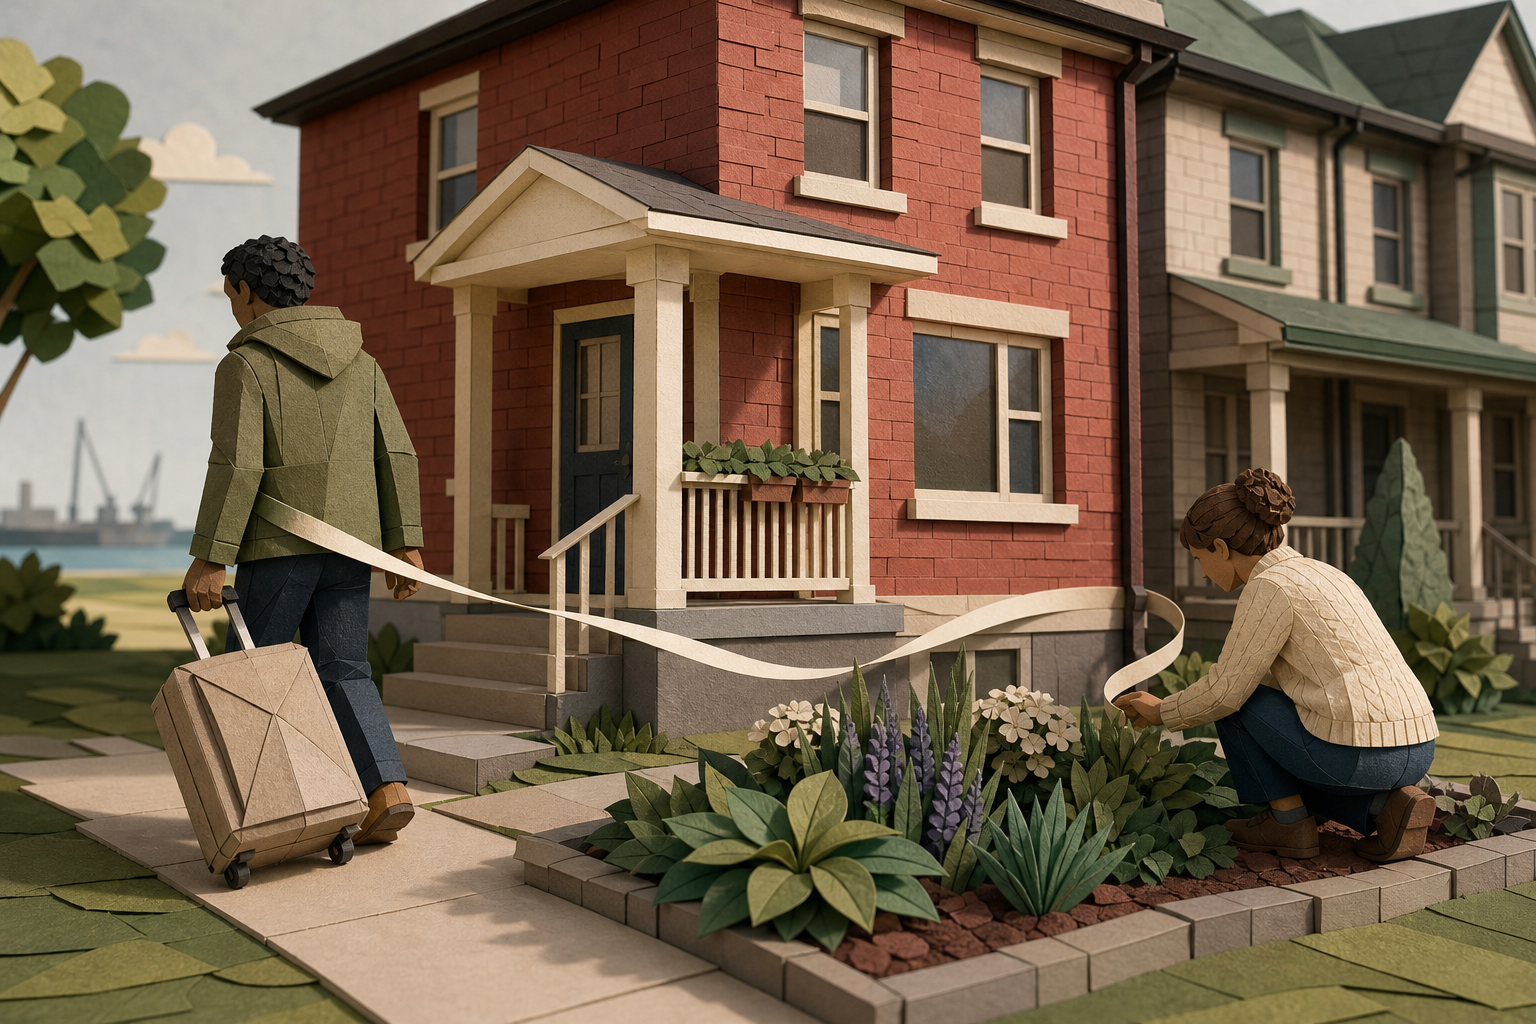
Picture two siblings, a few years after they bought a semi together in Grimsby. One has a new job in Ottawa and needs her share of the down payment back to buy there. The other loves the house, has a garden in, and never planned to leave. Neither of them did anything wrong, and both of them are about to find out that the deal they signed covered how to buy the house and said nothing about how one of them gets out. Planning for the day your futures split protects the purchase and the relationship.
If you've been texting listings back and forth with a friend or a brother, you probably know the relief of adding your savings together and seeing a real house come into reach. You may also know the small, awkward pause when you think about asking, "What if one of us wants out?" It feels like doubting the friendship before you've even moved in. Have that conversation anyway.
What happens when only one of you wants to sell
Pooling money works. Ontario's own guide to co-owning a home makes the point that combining resources can make ownership more affordable and open up neighbourhoods neither of you could buy in alone. Go back to the siblings. The same pooled down payment that got them in is now the thing they're fighting over. One needs that money freed up. The other needs the roof over her head.
Most co-buyers assume their ownership split will settle it. Say it's 50/50, or 60/40 because one person put in more. That percentage tells you who gets what share of the proceeds. It doesn't tell you what the house is worth today, who picks the appraiser, how long the person staying has to come up with the money, or who pays the real estate commission and legal fees if it has to be listed. Promising to be fair to each other leaves every one of those questions open, and they always come up at the worst moment.
Before you buy, sit down with an Ontario real estate lawyer and get answers to these in writing:
Why a buyout agreement may not get you off the mortgage
Suppose the siblings get all of that right. They agree on a value and a buyout figure, and the sister staying is ready to pay. The lender still has a say.
When you borrow together, lenders typically treat you as jointly and severally liable. That means each of you can be on the hook for the entire mortgage, regardless of your ownership share. Moving out doesn't change that, and neither does a private agreement between the two of you. The sister leaving for Ottawa stays responsible for the full debt until the lender formally releases her, usually through a refinance in the other sister's name alone. That only works if the sister staying qualifies to carry the whole mortgage on her own income. If she doesn't, the lender can say no, and the person who left may still see that debt counted against her when she applies for her next mortgage.
So the agreement needs one more piece: a clear fallback for when a buyout can't get approved, usually a sale on set terms. That's the lesson under all of this. Buying together only works long term if you also agree on how to stop owning together.
Writing down an exit plan doesn't mean you expect the friendship to fail. It gives you rules you agreed on while you still liked each other, so you never have to make them up in the middle of a fight. You can still buy together, and you can do it with a plan that holds when life moves one of you somewhere else.
A good first step is a short conversation with me about whether either of you could realistically take over the mortgage alone, and what that refinance would need. Pair it with a lawyer who can put your exit terms on paper, and you'll know before you buy how this ends well.
Read Next
Three TSX Earnings Reports, Three Different Answers to the Same Economy
GICs or High-Interest Savings: The Break-Even Math as the Bank of Canada Turns Hawkish
The Early Renewal Offer That Quietly Costs You Your Cheapest Months
Lower Payment or Same Payment at Renewal: One Choice Costs Five Figures